Silicon carbide is particularly in demand for applications in the automotive sector and the demand for SiC chips is increasing with the growing electrification of individual transportation. Naturally, Chinese players also want to benefit from this demand.
In China, there are increasing indications that a price war for SiC substrates could be imminent.
Henrik Bork, a longtime China correspondent for the Süddeutsche Zeitung and the Frankfurter Rundschau, is Managing Director at Asia Waypoint, a Beijing-based consulting agency specializing in China.
In China, there are increasing indications of a price war starting in the SiC substrate market. Although the long-term growth prospects in this segment remain good, a significant correction has been noticeable since the beginning of this year.
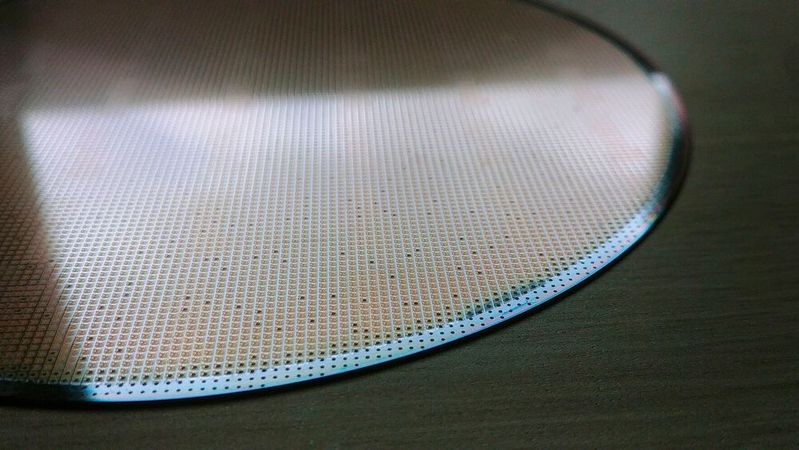
The increasing demand for SiC chips, mainly in the automotive industry, has recently led to a rapid expansion of production capacities, according to the Chinese specialist portal Huxiu. In China, sales of 6-inch SiC wafers surpassed the one million mark in 2023.
Nonetheless, the construction of production lines and factories continues. Between 2023 and 2032, the global market for SiC chips is expected to grow at an average annual rate of 11.6% (CAGR), according to a forecast by Emergen Research.
China's share of the global market continues to increase. While production in China last year accounted for 42% of the global market for silicon carbide substrates, this share is estimated to increase to about 50% by 2026, according to Huxiu.
Challenge with low prices
Chinese companies that have newly entered the SiC chip business, but have achieved surprisingly quick successes in the market, such as Tanke Blue, SICC, and Epiworld, are battling with low prices for market shares. This is one reason for the price adjustments. The other is the overall strong expansion of SiC substrate capacities worldwide, which has been pursued by both international and Chinese companies.
International SiC manufacturers, who particularly dominate the market for high-quality chips like those for the main inverters in electric cars, have already lowered their profit forecasts for SiC - even though they are still quite good.
STMicroelectronics, which was able to report a $500 million increase in its revenues in the segment last year, is predicting an increase in its revenues of "only" $150 million for the current year.
Infineon initially expected a 50% increase in its SiC revenues this year, but had to lower this to 20% in its latest growth forecasts. Japanese manufacturer Rohm also sees its SiC segment revenues growing less strongly, and Wolfspeed has temporarily stopped new greenfield investments in SiC production lines.
Focus on 8-inch wafer.
Last year, all manufacturers were still expanding strongly and increasingly shifting to the production of 8-inch wafers, which are widely expected to quickly replace the currently popular 6-inch wafers.
At least twelve projects for 8-inch wafer production expansions were carried out worldwide in 2023, as counted by the specialist medium Trendforce. Eight of them were by international, i.e., non-Chinese manufacturers like Wolfspeed, Onsemi, STMicroelectronics, Infineon, or Rohm. Three projects came from the Chinese companies Global Power Technology, United Nova Technology, and J2 Semiconductor.
Potential for cooperation
STMicroelectronics also invested in a new SiC plant in China together with the Chinese manufacturer Sanan Optoelectronics. He views the rapid growth of industry in China, including that of Chinese companies, not only as a risk but also as an opportunity, according to a report from the news agency Reuters. Recently, he was asked about this at an industry conference in London, where he explained the reasons for his company's investment in a joint venture with Sanan Optoelectronics.
"China is responsible for 15% of our revenues today. We know that China will be the fastest growing market in some markets, including the market for silicon carbide. Therefore, our penetration in China will increase," the CEO was quoted by Reuters.
At the same time, more and more Chinese manufacturers are entering this lucrative market. According to Trendforce, more than ten of them have already started small scale production of 8-inch wafers: Semisic Crystal Co., Jingsheng Mechanical & Electrical Co., SICC Co., Summit Crystal Semiconductor Co., Synlight Semiconductor Co., TanKeBlue Semiconductor Co, Harbin KY Semiconductor, IV Semitec, Sanan Semiconductor, Hypersics, and Yuehajin Semiconductor Materials Co. (sb)
Date: 08.12.2025
Naturally, we always handle your personal data responsibly. Any personal data we receive from you is processed in accordance with applicable data protection legislation. For detailed information please see our privacy policy.
Consent to the use of data for promotional purposes
I hereby consent to Vogel Communications Group GmbH & Co. KG, Max-Planck-Str. 7-9, 97082 Würzburg including any affiliated companies according to §§ 15 et seq. AktG (hereafter: Vogel Communications Group) using my e-mail address to send editorial newsletters. A list of all affiliated companies can be found here
Newsletter content may include all products and services of any companies mentioned above, including for example specialist journals and books, events and fairs as well as event-related products and services, print and digital media offers and services such as additional (editorial) newsletters, raffles, lead campaigns, market research both online and offline, specialist webportals and e-learning offers. In case my personal telephone number has also been collected, it may be used for offers of aforementioned products, for services of the companies mentioned above, and market research purposes.
Additionally, my consent also includes the processing of my email address and telephone number for data matching for marketing purposes with select advertising partners such as LinkedIn, Google, and Meta. For this, Vogel Communications Group may transmit said data in hashed form to the advertising partners who then use said data to determine whether I am also a member of the mentioned advertising partner portals. Vogel Communications Group uses this feature for the purposes of re-targeting (up-selling, cross-selling, and customer loyalty), generating so-called look-alike audiences for acquisition of new customers, and as basis for exclusion for on-going advertising campaigns. Further information can be found in section “data matching for marketing purposes”.
In case I access protected data on Internet portals of Vogel Communications Group including any affiliated companies according to §§ 15 et seq. AktG, I need to provide further data in order to register for the access to such content. In return for this free access to editorial content, my data may be used in accordance with this consent for the purposes stated here. This does not apply to data matching for marketing purposes.
Right of revocation
I understand that I can revoke my consent at will. My revocation does not change the lawfulness of data processing that was conducted based on my consent leading up to my revocation. One option to declare my revocation is to use the contact form found at https://contact.vogel.de. In case I no longer wish to receive certain newsletters, I have subscribed to, I can also click on the unsubscribe link included at the end of a newsletter. Further information regarding my right of revocation and the implementation of it as well as the consequences of my revocation can be found in the data protection declaration, section editorial newsletter.